
Difference Between Dividend Rate and Annual Percentage Yield
A dividend rate is the annual rate a credit union declares on an eligible account. APY goes one step further by including the effect of compounding. Credit union dividends generally come from the institution’s earnings, but rates can change. Access to funds depends on the account, while protection depends on whether the credit union is federally insured.
Dividend Rate vs APY at a Glance
The dividend rate and APY may appear beside each other in an account disclosure. Although the percentages can look similar, they do not represent exactly the same thing.
| Feature | Dividend rate | APY |
|---|---|---|
| What it shows | The declared annual rate | Estimated annual earnings after compounding |
| Includes compounding | No | Yes |
| Commonly displayed by | Credit unions | Credit unions, banks, and other financial providers |
| Best used for | Understanding the account’s stated rate | Comparing potential annual earnings |
| Can it change? | Yes, if the account has a variable rate | Yes, when the underlying rate changes |
| Does it guarantee earnings? | No | No, unless the account terms provide a fixed return |
The simplest way to remember the difference is that the dividend rate is the starting rate. APY shows what that rate could produce over a year after compounding.
What Is a Dividend Rate?
A dividend rate is the annual rate a credit union declares or expects to pay on an eligible account. According to federal credit union disclosure rules, the dividend rate does not reflect compounding.
Credit unions are member-owned financial institutions. Instead of having traditional customers and outside shareholders, they provide membership shares to eligible account holders. Dividends paid on these accounts represent a distribution of the credit union’s earnings to its members. You may see a dividend rate attached to:
- A credit union savings or share account
- A money market share account
- A checking or share draft account
- A share certificate
The account disclosure should explain whether the rate is fixed or variable, how frequently earnings are compounded, and when dividends are credited to the account.
What Does the Rate Tell You?
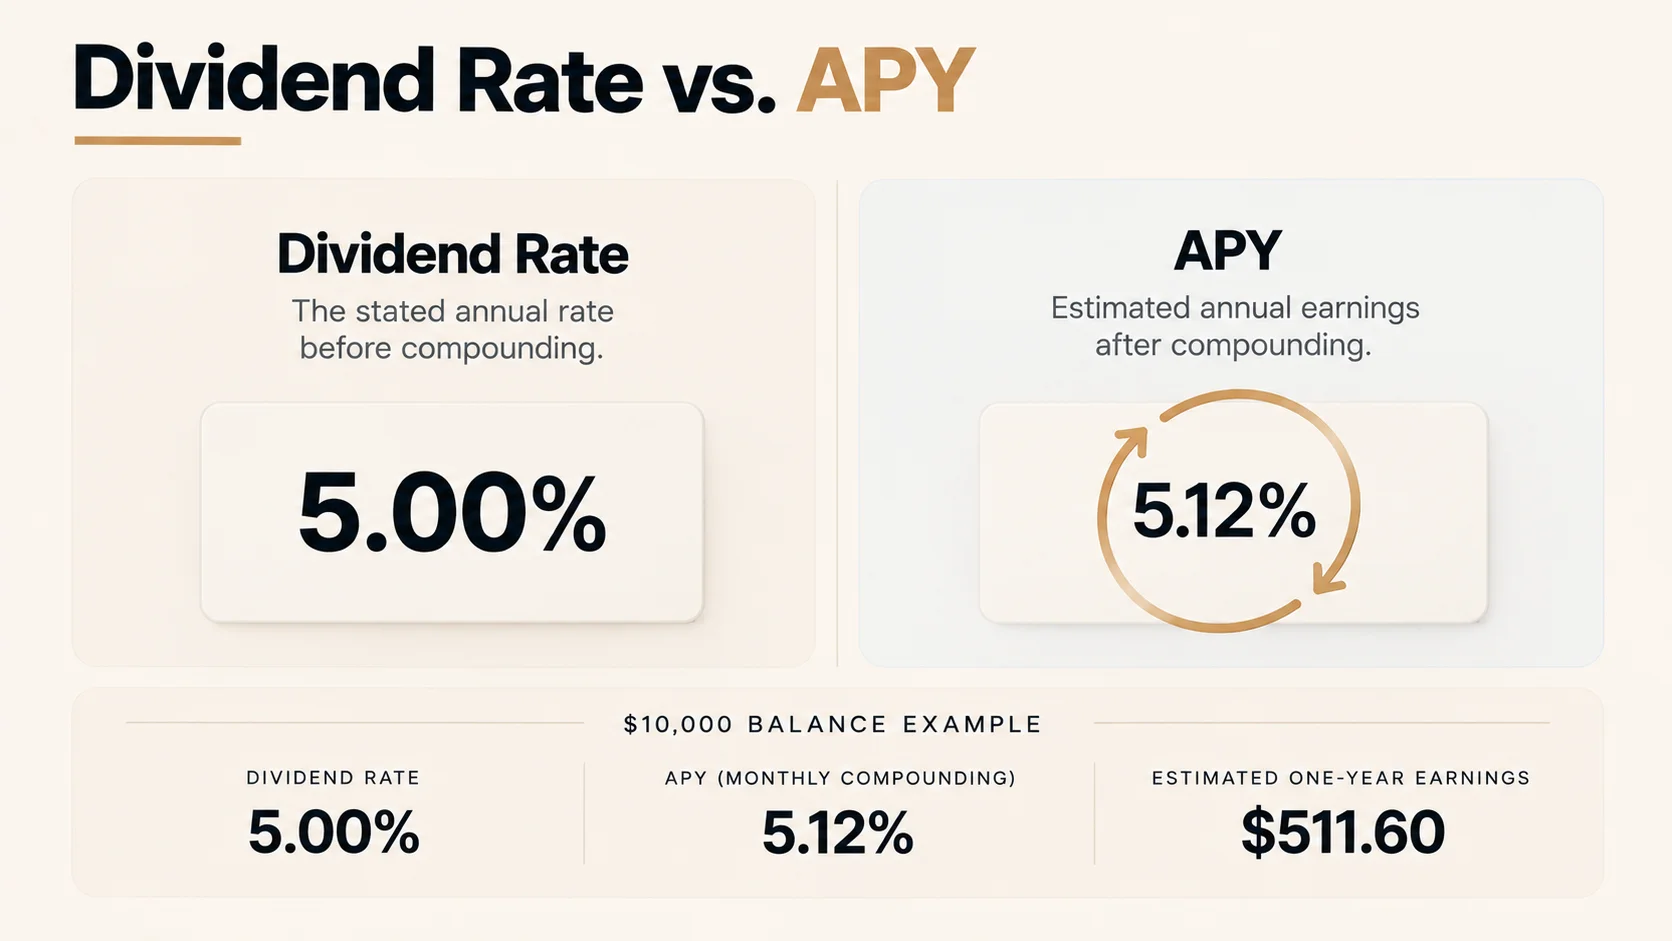
Suppose a credit union lists a 5.00% dividend rate. That percentage describes the annual rate before compounding is considered. It does not automatically mean the account’s APY is also 5.00%.
If earnings are regularly added to the balance, the account can begin generating earnings on both the original deposit and the amounts already credited. As a result, the APY may be slightly higher than the dividend rate.
The dividend rate is useful, but it does not provide the fullest picture of annual account growth.
What Is Annual Percentage Yield?
Annual percentage yield, or APY, estimates how much an account can earn over one year after compounding is included.
The National Credit Union Administration defines APY as a measure of the total dividends paid on an account based on the dividend rate and the frequency of compounding.
For example, two accounts could have the same dividend rate but compound on different schedules. If one compounds monthly and the other compounds daily, their APYs may be slightly different.
APY therefore provides a more useful figure for comparing accounts. It brings the rate and compounding schedule together in one percentage.
If you want a broader explanation of how this percentage works, read What Is APY on a Savings Account?.
APY Is an Estimate, Not a Promise
APY shows what an account could earn over a full year under the assumptions used in the calculation. It does not promise that every account holder will receive that exact amount.
Your actual earnings can differ if:
- The account has a variable rate that changes
- You make deposits or withdrawals during the year
- Your balance falls below a required level
- Fees are taken from the account
- You close the account before the year ends
APY remains the better comparison figure, but we still need to read the account terms behind it.
How Compounding Creates the Difference
Compounding happens when previously credited earnings become part of the balance used for future calculations.
An account might compound daily, monthly, quarterly, or annually. The more frequently it compounds, the sooner credited earnings can begin contributing to the next calculation. However, the difference between daily and monthly compounding is often small when the rate and balance are the same.
Here is a simple APY formula:
APY = (1 + dividend rate ÷ number of compounding periods) raised to the number of compounding periods − 1
The dividend rate must be written as a decimal before completing the calculation. A 5.00% rate becomes 0.05.
Example With Monthly Compounding
Suppose an account has:
- Starting balance: $10,000
- Dividend rate: 5.00%
- Compounding schedule: Monthly
- Compounding periods per year: 12
The calculation would be:
APY = (1 + 0.05 ÷ 12) raised to 12 − 1 APY = 0.05116 APY = approximately 5.12%
The estimated earnings would then be:
$10,000 × 0.05116 = approximately $511.60
Without compounding, a 5.00% annual rate on $10,000 would produce $500. Monthly compounding adds approximately $11.60 in this simplified example.
The credit union may calculate daily balances, retain more decimal places, and apply its own rounding rules. The amount shown on a statement may therefore differ slightly from a manual estimate.
Our guide to whether HYSAs compound monthly explains how different compounding schedules work.
How Dividend Rate and APY Affect Account Earnings
The dividend rate helps set the base calculation. APY translates that rate and the compounding schedule into an estimated annual percentage.
Consider two accounts:
| Account | Dividend rate | Compounding | APY |
|---|---|---|---|
| Account A | 5.00% | Annually | 5.00% |
| Account B | 5.00% | Monthly | Approximately 5.12% |
Both accounts advertise the same dividend rate, but Account B has a higher APY because it compounds more frequently.
That does not always mean Account B will produce more money for you. A monthly fee, minimum balance rule, withdrawal restriction, or rate condition could change the result. An attractive APY is only valuable when you can meet the account requirements without losing a meaningful part of the earnings.
Your balance also matters. A higher APY produces more dollars on a larger balance, but the percentage itself does not change simply because you deposit more, unless the provider uses balance tiers.
For more examples using different balances and rates, see How Much Does a High-Yield Savings Account Earn?.
APY and the Amount You Actually Earned
APY is normally shown before you open an account. It is a forward-looking figure based on the account’s current terms.
Your statement may also show annual percentage yield earned, sometimes shortened to APYE. This is based on what the account actually earned during a statement period. It can reflect balance changes, credited dividends, and the number of days covered by the statement.
APY helps you compare offers. APYE helps you review past account performance.
Can Dividend Rates and APYs Change?
Yes. Variable dividend rates may rise or fall after an account is opened. When the dividend rate changes, the corresponding APY changes as well.
A credit union may consider market conditions, its financial performance, available earnings, funding needs, and internal rate decisions. A change does not always happen immediately after broader market rates change.
Fixed-rate share certificates work differently. Their rates may remain unchanged for a defined term, provided the account is kept under the agreed conditions. Withdrawing early could result in a penalty, so the higher certainty comes with reduced access.
If easy access matters, compare the terms carefully before choosing between a flexible share account and a certificate. You can also read Do High-Yield Savings Account Rates Change? for more detail on variable rates.
Which Number Should You Use When Comparing Accounts?
Use APY when you want to compare the estimated annual earnings of similar accounts. Because it includes compounding, it creates a more consistent basis for comparison.
The dividend rate still matters. It tells you the rate used before compounding and may help you understand why the APY changes. However, comparing dividend rates alone can hide differences between compounding schedules.
Along with APY, check:
- Monthly and account maintenance fees
- Minimum opening and ongoing balances
- Requirements for receiving the advertised APY
- Transfer and withdrawal rules
- Whether the rate is fixed or variable
- How eligible balances are protected
A high-yield digital savings account with a slightly lower APY could produce a better practical result if it has no monthly fee and fewer balance requirements. Similarly, a convenient high-yield savings app may suit you better if access and account management matter more than a small difference in APY.
Our guide to what makes a good savings rate can help you judge whether an advertised APY is competitive.
Check What Produces the APY
The same term can appear across different financial products, but that does not make the products equal.
At a federally insured credit union, qualifying share accounts generally receive protection through the National Credit Union Share Insurance Fund. The standard coverage is $250,000 per share owner, per insured credit union, for each account ownership category.
A digital savings platform or online savings app may use a different structure. Some companies partner with insured financial institutions, while others offer investments whose value can rise or fall.
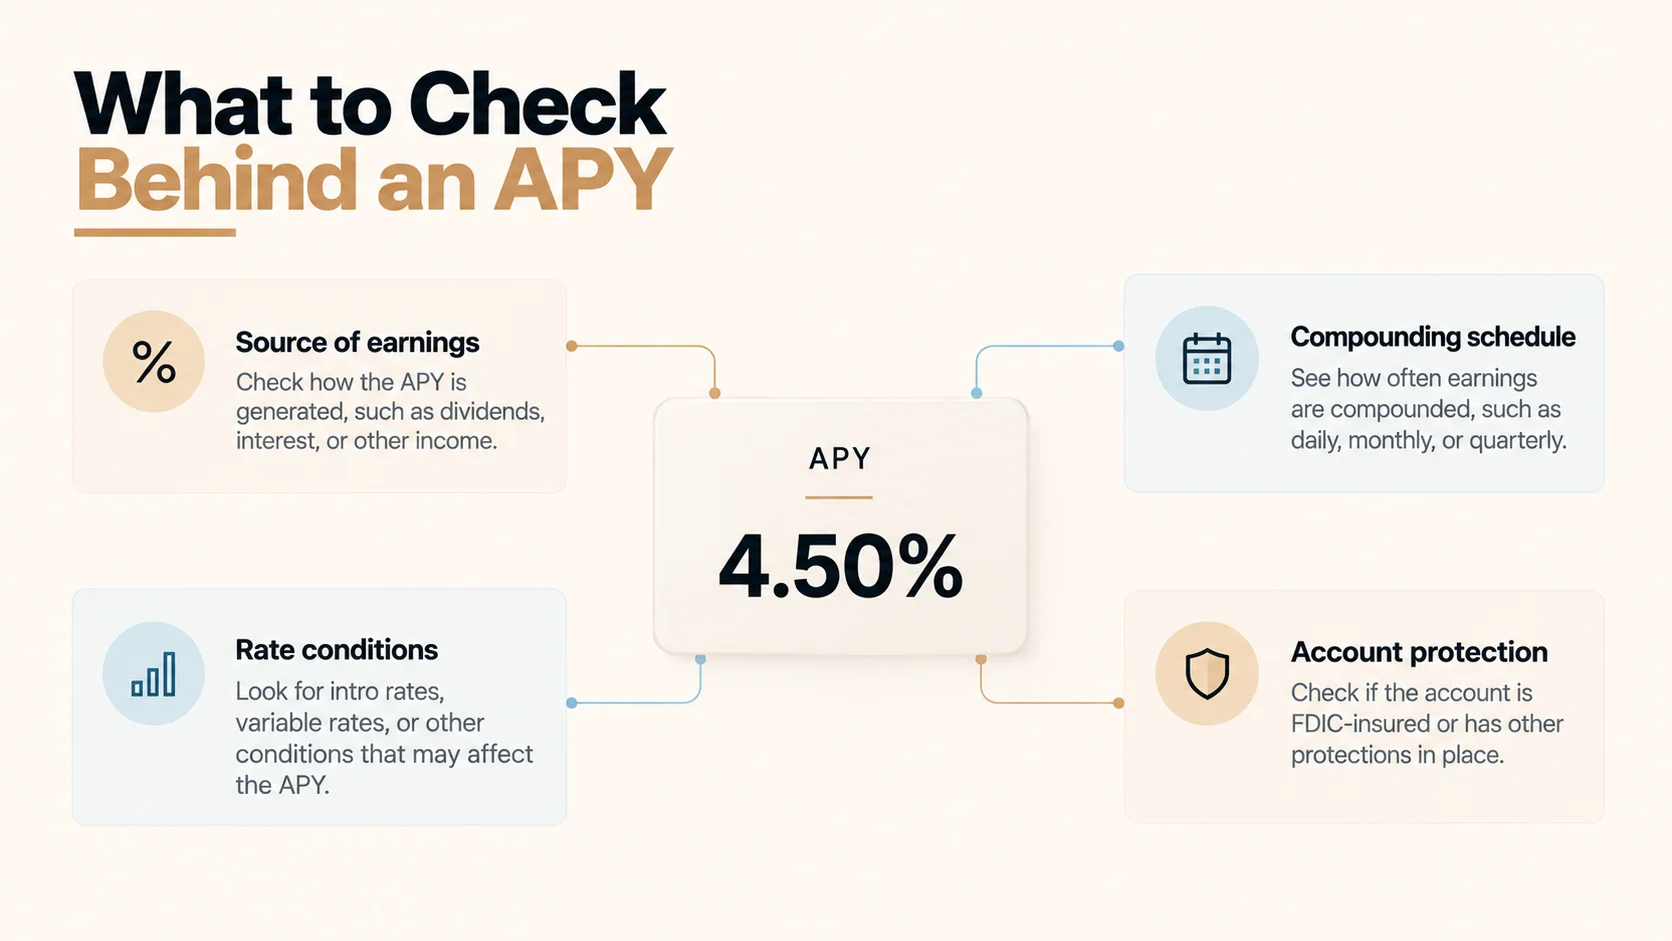
A high-yield investment platform may also display a projected APY. That figure may come from rental income, assets, lending, or another source rather than a credit union dividend. Before comparing percentages, confirm:
- What produces the earnings
- Whether the APY is fixed, variable, or projected
- How quickly you can access your funds
- What fees apply
- Whether the balance has federal protection
- Whether the underlying value can fall
This context matters as much as the percentage itself.
Put Your Dollars Into Something Real
With PureFi, your projected earnings come from shares of real homes with tenants. Choose your properties from your phone, review the documents, and see every fee before you confirm.
Learn more about how PureFi can help you own real estate shares or download the app to get started today.
Up to 6% APY is projected, variable, and not guaranteed. Property shares can lose value. PureFi is not a bank, and its balances and real estate shares are not covered by FDIC insurance or another government deposit scheme.


